
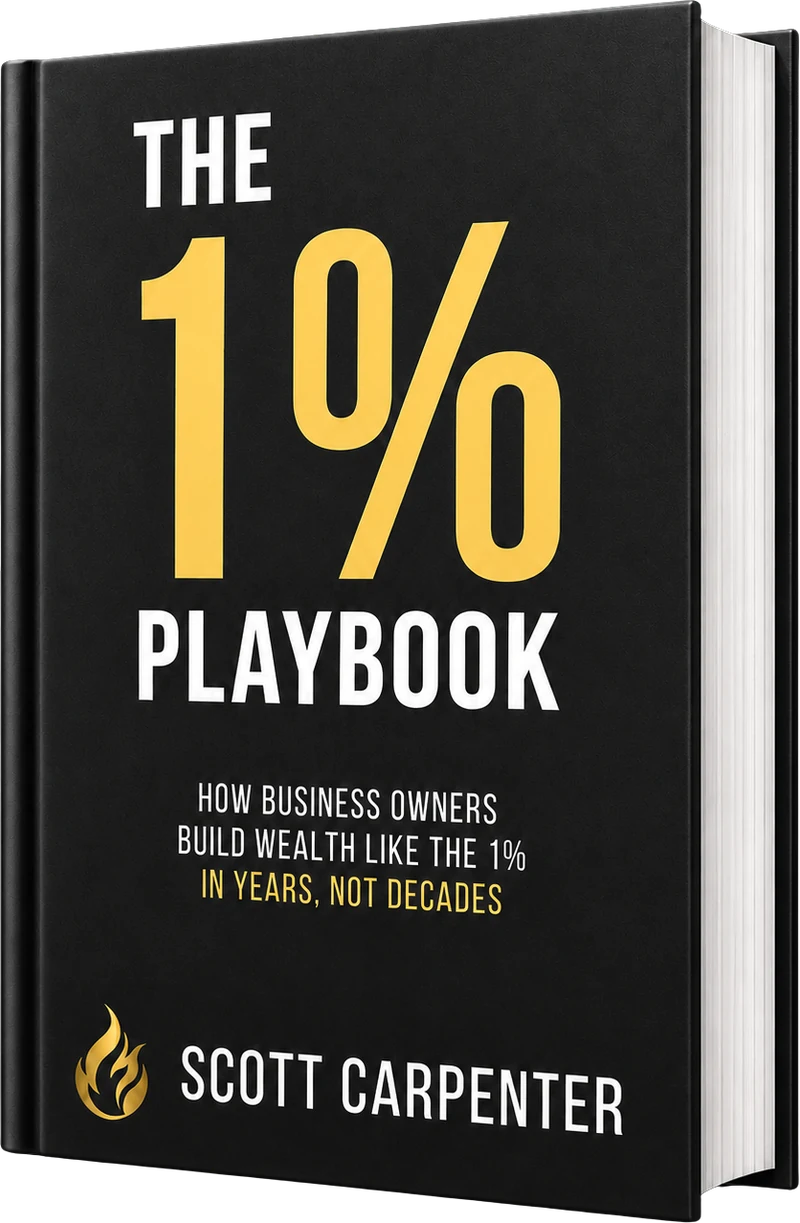
The 1% Playbook · Coming soonHow business owners build wealth like the 1%. In years, not decades.
Hope is not a strategy. Scott's new book shows you exactly how to turn business profit into passive income.
Get on the list and Scott will send you the audiobook free.
The 1% aren't smarter than you. They just have a different playbook.
The advice you were given was built for the bottom 99%.
Never buy a Starbucks. Sock it all away in a 401(k) you can't touch until 65. Hope you don't run out before you die.
That's great advice if you want to stay in the middle class.
If you want to join the 1%, you have to do things differently. Most owners already know that. They just don't have a plan.
This book is the plan.
- Store your wealth in your own private bank
- Use the same dollars to invest in cash-flowing assets
- Use the extra cash flow to grow your net worth faster
- Pay less to the IRS and protect it from creditors and lawsuits, when properly structured
I started with three foreclosures and destroyed credit.
Massive debt. No money. Once I got my feet back under me, I vowed I'd never worry about money again.
So I ran this playbook with the extra cash from my training studios. I funded my private bank and used the same dollars to buy real estate.
Scott's own numbers, not typical. Projections use the carrier's current dividend scale, and dividends are not guaranteed. See the full breakdown.
I'm not a wealth advisor. I'm a gym owner.
I'm never going to ask you to hand me your money so I can invest it for you. I'm going to teach you to do it yourself.
I make my money the way I always have: the businesses I own. I built personal training studios, and I coach other gym owners on how to actually turn a profit.
When the owners I coached started throwing off real cash, they had no idea what to do with it. So I taught them.
Every time one of them came back with a policy they'd bought somewhere else, it was garbage. Bloated with fees. Built to pay the agent.
So I got licensed and started building them the right way. Now I teach it because everybody deserves wealth they never have to worry about.
Three steps. Start wherever you want.
Every year you wait is a year you don't get back.
Every year your money sits where the 99% keep theirs, it's working for someone else. Pick a step. Any step. Just take one.
Scott provides wealth education and is a licensed life insurance agent. He is not a registered investment advisor or a tax advisor, and nothing here is investment, tax or legal advice.